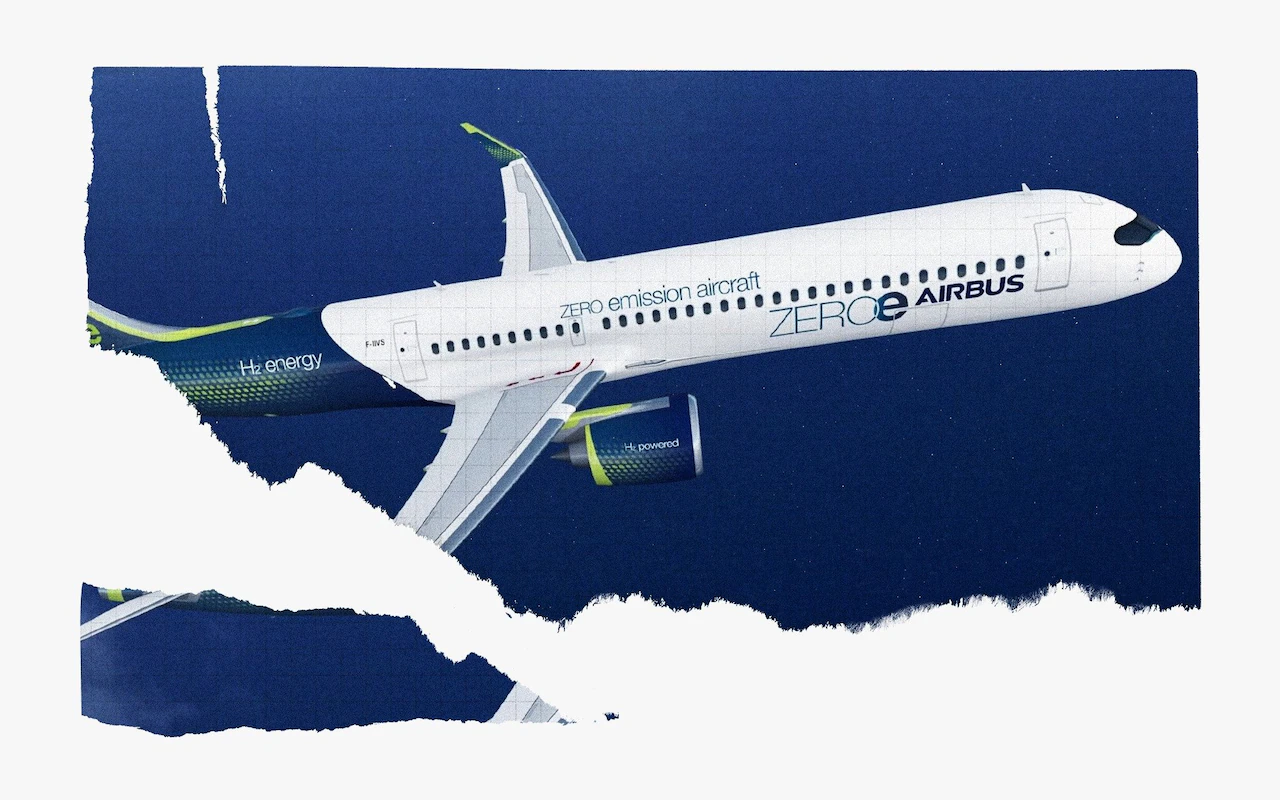
UK hydrogen deployment leaves investors waiting and fleets reluctant to order vehicles without dependable fuel. Leading European projects offer a lesson: production support works better when customers and infrastructure can commit alongside it.
Summary
The EU framework combines production support with industrial demand targets and refuelling obligations. Germany and the Netherlands also show the advantage of existing industrial customers. Britain’s substantial production funding needs firmer connections to fuel purchases, fleet procurement and infrastructure investment to accelerate commercial deployment.
Britain’s hydrogen problem reaches the balance sheet before it reaches the road. A fleet will hesitate to buy trucks without a reliable fuel contract. A producer needs committed sales before financing a plant. A station needs enough vehicles to recover its investment. When those decisions run on separate timetables, investment slips, infrastructure risks sitting idle and low utilisation keeps delivered hydrogen expensive.
The EU has developed stronger mechanisms for connecting supply with demand: production premiums sit alongside industrial consumption targets and refuelling obligations. German and Dutch industrial projects show how an established customer can make that framework investable. Britain has put substantial funding behind production, but the commercial commitments needed to put hydrogen into vehicles remain harder to assemble. My conclusion is that UK deployment will accelerate when support and procurement are organised around customers who can commit, with fuel, stations and vehicles ready together. Europe’s own delays show why regulation alone cannot finish the job.
UK hydrogen deployment: awards, investment and operation
The UK’s first Hydrogen Allocation Round, HAR1, launched in July 2022 and selected 11 projects in December 2023, totalling 125 MW of hydrogen output capacity. The first three support contracts were issued in December 2024; ten contracts had been signed by July 2025. Those contracts support production revenue. They are a step towards investment, rather than evidence that all the plants are running.
The Climate Change Committee’s July 2026 report records up to 117 MW under signed agreements after Whitelee’s agreement was terminated in December 2025. Other projects were moving through investment decisions, construction and operation. Customers and lenders must stay committed through each stage, even as delivery dates change.
HyMarnham reports full-capacity commercial operation from January 2026 at its 15 MW electrolyser installation. West Wales reached final investment decision on 11 March 2026 for a 20 MW electrolyser, with commissioning expected in early 2028. Britain can deliver projects, but the elapsed time from funding application to fuel supply is commercially significant.
HAR2 shortlisted 27 projects in April 2025. The 2025–26 government project dataset still recorded allocation pending at year-end, with business-case approval delays affecting negotiations. A shortlist gives developers another process to complete while prospective buyers decide how long they can wait.
Germany’s EWI/BDEW monitor, using 31 March 2026 data, records 181 MW of operating electrolysis capacity and another 1,271 MW at final investment decision or under construction. More than 7.2 GW planned for 2030 had no announced investment decision. Germany has a more developed committed pipeline, but most of its ambition still has to become operating plant.
Existing customers make projects easier to finance
Shell’s project update makes the distinction especially clear. Holland Hydrogen 1 in the Netherlands is a 200 MW electrolyser under construction, with commissioning expected to begin in 2027. Germany’s 100 MW REFHYNE 2 took its investment decision in 2024 and is under construction for expected startup in 2027. REFHYNE 1’s 10 MW unit has operated since 2021.
Both larger projects have a defined destination: Shell’s own refining operations. Replacing hydrogen already consumed on site reduces the need to find a new market or build dispersed distribution. Electricity procurement, engineering and customers can be coordinated within one business. West Wales also targets industrial uses: this advantage is available in Britain, too, and helps explain which projects become financeable.
An independent fleet supplier must negotiate volumes, price, delivery dates and remedies for supply failures. Its customer must judge vehicle availability, maintenance and freight revenue over the same period. Lenders reviewing this technical and commercial investment case need to know who carries the risk if one part arrives late.
European policy reaches further along the chain
The European Hydrogen Bank supports production through premiums on verified hydrogen output. Alongside it, the revised Renewable Energy Directive, RED III, requires renewable fuels of non-biological origin, or RFNBOs, to supply at least 42% of qualifying industrial hydrogen use by 2030 and 60% by 2035. This gives prospective buyers a compliance reason to plan purchases.
RED III’s industrial target is a national obligation, with exclusions and conditional reductions; it is not an identical quota for every factory. Hydrogen for conventional transport-fuel production, for example, is excluded from the industrial denominator. National implementation remains uneven, so the commercial effect depends on the country and customer. Refinery demand and industrial compliance demand are distinct routes to securing buyers.
For road transport, Article 6 of the Alternative Fuels Infrastructure Regulation, AFIR, requires publicly accessible hydrogen stations by 31 December 2030 along the TEN-T core road network, Europe’s principal transport corridors: no more than 200 km apart, with at least one-tonne daily capacity and a 700-bar dispenser. Each urban node must also have a public station. On qualifying roads carrying fewer than 2,000 heavy vehicles daily, capacity can fall by up to 50% where deployment lacks a socioeconomic justification; spacing and pressure requirements remain. Specified island exemptions also apply.
These measures give producers, buyers and station investors more explicit requirements against which to plan. The UK has demand measures too: its Renewable Transport Fuel Obligation rewards eligible low-carbon fuel, and HGV demonstrators support vehicles and infrastructure. Yet these do not create an AFIR-style network obligation or remove the need for individual fleet commitments. HAR1’s over £2 billion of revenue support over 15 years is substantial; its commercial impact depends on connecting that support to usable demand.
| Commercial link | UK | EU framework and selected markets |
|---|---|---|
| Production support | HAR revenue contracts support low-carbon output. | Hydrogen Bank premiums support renewable output; national schemes also differ. |
| Demand creation | RTFO rewards eligible fuel; customers still negotiate purchases. | RED III sets qualifying industrial RFNBO targets, implemented nationally. |
| Refuelling | HGV demonstrators support selected projects. | AFIR requires core-corridor and urban-node stations by 2030, with flexibility. |
| Industrial offtake | West Wales targets industrial users; commissioning expected early 2028. | Shell’s Dutch and German projects are designed for existing refinery demand. |
| Investment certainty | Support contracts help; customer, fuel and vehicle commitments must align. | EU obligations help planning; integrated customers strengthen specific projects. Delays persist. |
| Deployment stage | HyMarnham reports operation; West Wales has FID. HAR2 has a shortlist. | Germany: 181 MW operating, 1,271 MW at FID/construction (electrical input, March 2026). Shell’s large plants remain under construction. |
Electricity and infrastructure still set the economics
An electrolyser splits water into hydrogen and oxygen using electricity. DESNZ’s September 2026 release puts April–June manufacturing electricity prices at 17.4p/kWh (£174/MWh), excluding the Climate Change Levy. Individual hydrogen projects face different bills: renewable-power procurement, network charges, grid connections and operating hours determine their economics.
At an illustrative 50 kWh/kg, £50/MWh electricity contributes £2.50/kg of hydrogen and £100/MWh contributes £5/kg. This is a relatively efficient assumption: DOE’s system benchmarks give 55 kWh/kg for 2022 and a 51 kWh/kg target for 2026. Capital, maintenance, compression, storage and delivery come on top. These are production electricity costs, not pump prices; delivered hydrogen economics depend heavily on utilisation.
Cheap intermittent power can also mean fewer kilograms over which to recover fixed costs. A suitable grid connection and dependable supply matter as much as the headline tariff. UK transport and storage support includes over £500 million for a first regional network; the CCC envisages it from 2031. Fleet projects still need near-term distribution and depot refuelling arrangements.
What would accelerate UK hydrogen deployment?
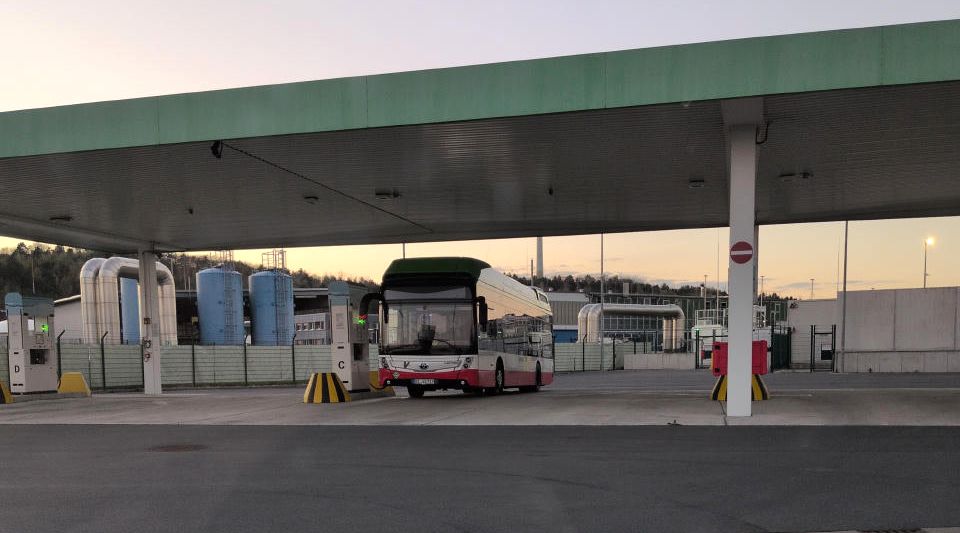
Europe’s station closures expose the same commercial limits. H2 MOBILITY announced closure of 14 German stations at the end of 2025, explaining that the passenger-car market had disappointed and older sites lacked the capacity required by commercial vehicles. Its shift towards regional demand clusters, buses and trucks is a response to throughput and equipment requirements.
H2 MOBILITY’s October 2026 price cuts at 15 additional stations show how renewable hydrogen and emissions-quota revenues can improve selected sites’ economics. The lesson is to build around credible local demand and appropriate station capacity, rather than assume that network coverage automatically creates customers.
My commercial conclusion is that Britain should organise investment around customers prepared to sign fuel contracts. Identify contracted fleets and predictable routes first, then align production, distribution, refuelling and vehicle procurement to a shared opening date. Long-term supply arrangements need enforceable volumes, pricing, uptime and backup-fuel provisions. Industrial anchor customers can provide initial throughput while transport demand grows, where location and fuel specifications make that practical.
Production support should test whether those linked commitments are credible before treating a project as ready for delivery. Fleet operators, fuel suppliers, infrastructure owners and financiers should agree who bears low utilisation, late commissioning and vehicle residual-value risk. A fleet total-cost-of-ownership assessment can expose how those assumptions change the route economics; the wider commercialisation challenge is making the complementary investments useful together.
Hydrogen has a credible role where intensive duty cycles, turnaround or payload requirements make available battery options commercially difficult and dependable low-carbon fuel can meet the route’s costs. Britain should concentrate effort on those cases, comparing them with workable battery alternatives. Faster deployment will come from making the next fleet and fuel investment mutually dependable, then repeating a model that customers will pay to use.
Assess the deployment case
I co-founded and formerly led Element 2, working on the fuel, vehicle, site and customer dependencies behind hydrogen refuelling for heavy transport. My hydrogen infrastructure advisory work applies that experience to project viability, offtake, utilisation and investment sequencing. For vehicle and route decisions, see fleet deployment economics and transition assessment.
Source notes: Evidence is limited to 13 October 2026. HyMarnham’s operator dates full-capacity commercial operation to January; the CCC records operations starting in April. HAR1 capacity is hydrogen output on a higher-heating-value basis; EWI and the named electrolyser sizes are electrical input. They do not establish a UK/Germany deployment ratio. HAR2’s official materials available at the cut-off identify a shortlist, rather than a confirmed award round.
RED III also excludes hydrogen used to produce biofuels, qualifying residual-gas recycling and industrial by-product hydrogen; eligible countries can reduce the target by 20% subject to renewable-energy progress and fossil-hydrogen limits.
Sources
Primary evidence: HAR1 awards; first agreements; contract update; CCC progress; NISTA HAR2 data; HyMarnham; West Wales; EWI/BDEW; Shell.
Policy and costs: Hydrogen Bank; RED III guidance; national implementation; AFIR; DESNZ prices; DOE efficiency; UK infrastructure support; station closures; October price cuts.